Due to the tightening of social distancing measures, Suntec Real Estate Investment Trust (“Suntec REIT”) is still struggling to see the light at the end of the tunnel. The REIT is tapping the bond market with a new perpetual note, most probably to help with its refinancing needs.
About the bonds
These subordinated perpetual securities are issued by Suntec REIT under the USD 2b Euro Medium Term Securities programme dated 15 Oct 2020. The net proceeds will be used for general corporate purposes of Suntec REIT, refinancing of existing borrowings, financing or refinancing acquisition and/or investments and financing any asset enhancement works.
The bonds are first callable in June 2026 and will reset to the prevailing 5Y SGD swap offer rate (“SOR”) or the successor rate and initial credit spread if not called. The perps are callable every six months thereafter. Any deferred distributions are non-cumulative and the securities have embedded dividend stopper features.
About Suntec REIT
Suntec REIT is managed by ARA Trust Management (Suntec) Limited. The REIT was listed on the Singapore Exchange on 9 Dec 2004 and has a market cap of SGD 4.23 billion as at 7 Jun 2021.
Its portfolio comprises office and retail properties in Suntec City, 66.3% interest in Suntec Singapore Convention & Exhibition Centre (“Suntec Singapore”), one-third interest in One Raffles Quay (“ORQ”), one-third interest in Marina Bay Financial Centre Towers 1 and 2 and the Marina Bay Link Mall (“MBFC Properties”), and 30.0% interest in 9 Penang Road.
It also has equity interest in properties in Australia and UK. There are 10 properties in total in the portfolio – 4 in Singapore, 2 in Sydney, 2 in Melbourne, 1 in Adelaide, Australia and 1 in the United Kingdom.
2020 and 1Q21 Operating results
For the full year of 2020, gross revenue declined by 14.0% YoY to SGD 315.39m while property expenses lowered by 14.4% YoY to SGD 111.26m resulting in a net property income (“NPI”) of SGD 199.88m, 15.4% lower than 2019’s. Other properties that Suntec REIT has an interest in, e.g. ORQ and MBFC Properties, also performed poorly in 2020, clocking in an income of SGD 56.39m, 64.3% lower than 2019’s. Net income thus declined by 55.8% YoY to SGD 115.08m for 2020. However, total return before tax fell to -SGD 115.32m due to fair value losses in investment properties and financial derivatives.
For 1Q21, operating performance was much better due to new acquisitions and much better results for the office segment. Net property income for 1Q21 increased by 10.2% YoY to SGD 59.5m as total income from the office segment including joint venture increased by 29.9% YoY to SGD 72.6m. The retail and convention segment saw total income declined by 24.1% and 47.1% to SGD 17.3m and -SGD 2.5m respectively.
However, Suntec REIT’s office portfolio for both Singapore and overseas have registered higher than average committed occupancy rate and higher rental rates. 22.2% of office leases at Suntec City are expiring this year which may be renewed at higher rental rates. This will be beneficial for the REIT.
Its retail and convention segments are likely to continue to be in the doldrums until 3Q21 when Singapore has almost completed its vaccination drive. Footfall will rise by then and intermittent restriction measures will hopefully be less frequent. The management also forecasts mall traffic to recover to about 80% of 2019’s level by end-2021.
Due to the new acquisitions and low base effect, growth in net income should continue to be positive for the year ahead, mainly driven by the office segment. While the retail segment will take a longer time to recover, management seems to be optimistic on its recovery towards its 2019 levels.
Credit profile
Suntec REIT issued SGD 200m of the SUNSP 3.800% Perpetual Corp (SGD) in October 2020 under the terms of the USD 2b Euro Medium Term Securities Programme dated 15 Oct 2020. Treating the perpetual notes as debt and combining its value with the SGD 678.2m of current borrowing and SGD 4.15b of non-current borrowings as at the end of December, we estimate total indebtedness to have increased from SGD 3.63b in 2019 to SGD 5.03b in 2020.
Our approximate gearing measure, defined as total borrowings and perpetual securities over total assets grew from ~36.2% in 2019 to ~44.7% in 2020. In the meantime, net borrowings to equity reached as high as ~77.8% in 2020. According to the REIT’s 1Q21 business update, aggregate leverage ratio – calculated as the ratio of total borrowings to the value of the deposited property increased marginally from 44.3% on 31 Dec 2020 to 44.4% on 31 Mar 2021.
We are comfortable with the REIT’s liquidity profile considering that it had SGD 227.5m of cash and cash equivalents, SGD 750m of undrawn facilities and SGD 678.2m of current borrowings. The amount of facilities may have dropped to SGD 630m in March 2021 but it is sufficient to cover its SGD 527m of borrowings for the remainder of this year. The capital from this perpetual note offering may also help to cushion some of the pandemic's impact on the REIT's gearing. Furthermore, we believe that gearing will also be mitigated by Suntec REIT opting to receive part of its management fees in the form of units.
Adjusted interest coverage ratio, as per company, improved from 2.6x on 31 Dec 2020 to 2.7x on 31 Mar 2021. Our measure of estimated EBITDA to interest multiple fell from ~3.13x in 2019 to ~1.97x in 2020, which are at a reasonable level.
Relative valuation
We compare Suntec REIT to other real estate issuers that have also issued perpetual securities (“perps”). In the table below we have AIMS APAC REIT (“AAREIT”), ARA Asset Management Ltd (manager of Suntec REIT, “ARASP”), ESR Cayman Ltd (“ESRCAY”), Lendlease Global Commercial REIT (“LREIT”) and Starhill Global REIT (“SGREIT”).
Table 1: Credit ratios of other REITs
|
SUNSP* |
LREIT |
AAREIT* |
SGREIT |
ESRCAY |
ARASP |
|
|
Leverage ratio (total debt/total assets) |
44.40% |
34.74% |
33.90% |
35.68% |
43.33% |
18.36% |
|
Adjusted. leverage ratio (incl. perps) |
44.70% |
47.42% |
43.96% |
38.88% |
46.79% |
45.74% |
|
Interest coverage ratio (x) |
~1.97 |
2.75 |
4.00 |
3.18 |
3.88 |
3.64 |
Source: Companies’ financial statements/presentations,
Bloomberg Finance L.P., iFAST estimates
Data as of 31 Dec 2020, *as of 31 Mar 2021.
ARA Asset Management has a large proportion of perpetual securities on its balance sheet compared to other issuers. In Table 1, we include perpetual distributions in ARA’s interest coverage ratio (EBITDA/interest expense).
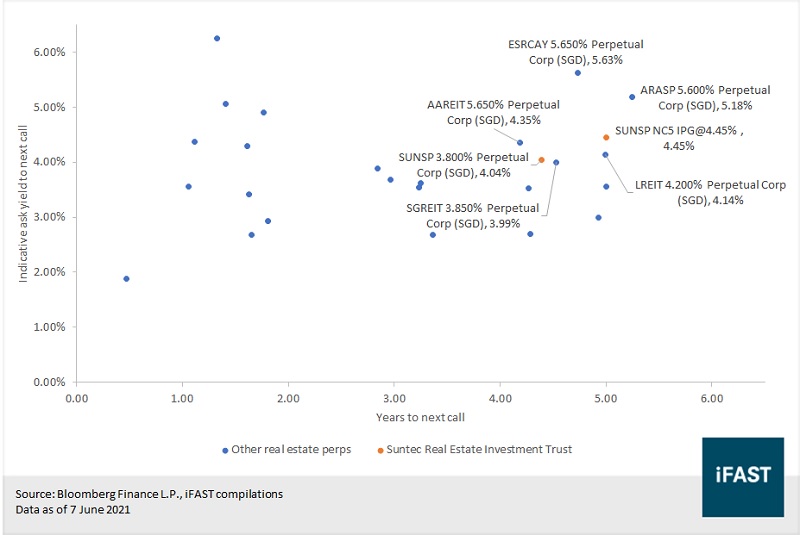
From Table 1 and Figure 1, we observed that the smaller REITs such as LREIT, AAREIT and SGREIT have better credit ratios but their yields-to-call (“YTC”) do not differ much from the Suntec’s perps. For example, the asset values of LREIT’s and AAREIT’s are about 15% of Suntec REIT’s total assets.
Figure 1: Perpetual bonds issued by REITs and real estate companies
We
estimate that the final price guidance (“FPG”) of Suntec REIT’s new NC5 perps
to be 4.20%. With a potential 4.2% yield, investors may want to consider other
SGD perps for their better credit ratios and higher yield.
Perps issued by ESRCAY and ARASP are also more attractive at their higher YTCs, although they may not be entirely focused in office or retail properties. Furthermore, there are also similar yielding bonds with a shorter first call dates. While an IPG of 4.45% looks attractive at first glance, we estimate that the final distribution rate to be around 4.2%. Due to the small difference in yields, we feel that investors may also simply consider the SUNSP 3.800% Perpetual Corp (SGD) at its YTC of 4.04%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ARASP 5.200% Perpetual Corp (SGD), ESRCAY 5.65% Perpetual Corp (SGD) and ESRCAY 6.750% 01Feb2022 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!